New Home Purchase
Own Your Slice of Heaven With Your New Home Purchase
The benefits of home ownership reach far and wide. Not only are there financial benefits to owning a home but there are emotional, social, and societal benefits as well! Take a look at all home ownership has to offer. Also, keep in mind that we can help finance your dreams with some programs requiring as low as a 3% down**.
Learn more about the mortgage process so that when you begin shopping for a home, you know how much you can afford.
Loan Options
Conventional
A Conventional Purchase requires as little as 3% down payment and cancellable monthly private mortgage insurance. Both Fixed Rate & Adjustable Rate Mortgage options are available. It's recommended you have a credit score of 620 or higher when you apply for a conventional loan.
FHA
If you're a first-time homebuyer and your credit score isn't great, an FHA loan may be a great option for you. FHA loans allow for as little as 3.5% down and have options available for buyers with credit scores as low as 600.
VA
Veterans and active duty military may qualify for 100% financing (0% down payment) with no monthly mortgage insurance through the VA loan program. There is no minimum credit score requirement.
DTI Ratio
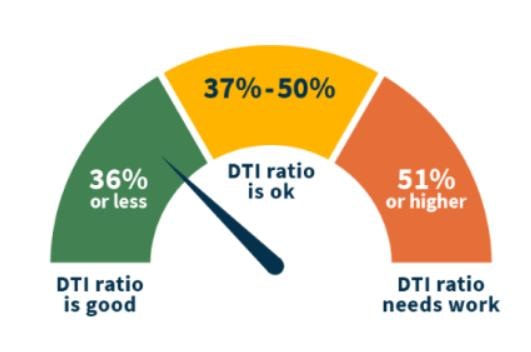
DTI (debt-to-income) ratio is the percentage of your gross monthly income that goes toward paying your monthly debts. To qualify for a mortgage, lenders typically require that you have a debt-to-income ratio of "43/49." This means that no more than 43% of your total monthly income (from all sources, before taxes) can go toward your new mortgage payment, and no more than 49.99% of your monthly income can go toward your total monthly debt (including your new mortgage payment).
If you find your DTI ratio is on the high side, you may want to work on decreasing it long before applying for a mortgage. Please consult our Loan officer today for accurate DTI information!
Credit Score
A measure of creditworthiness of an individual, FICO scores are widely used by most lenders in their credit decision. If your bank, credit card issuer, auto lender or mortgage servicer participates in FICO® Score Open Access, you can see your FICO® Scores, along with the top factors affecting your scores, for free.
The minimum credit score needed for most mortgages is typically around 620. However, government-backed mortgages like FHA loans typically have lower credit requirements. Our Loan Officer can help you figure out what mortgage options would best fit your situation and lifestyle.
Down Payment
Your down payment plays an important role when you're buying a home. A down payment is a percentage of your home's purchase price that you pay up front when you close your home loan. Lenders often look at the down payment amount as your investment in the home.
Not only will it affect how much you'll need to borrow, it can also influence: 1) Whether your lender will require you to pay for private mortgage insurance (PMI). 2) Your interest rate.
Please consult our Loan Office today for the best finance options with downpayments as low as 3%**